


A company’s first statutory audit in Singapore is often its most demanding one. Opening balances have never been tested, documents are spread across mailboxes and shared drives, and the people who set up the company may have moved on. The good news is that most of the effort can be planned. This guide sets out what to prepare and when, working back from the deadlines that matter.
Key deadlines at a glance
| Item | Timing (non-listed company) |
|---|---|
| Appoint an auditor | Within three months of registration, unless exempt from audit (ACRA) |
| Estimated Chargeable Income (ECI) | Within three months after the financial year end, unless the waiver conditions are met (IRAS) |
| AGM | Within six months after the financial year end, unless the company does not need to hold one (ACRA) |
| Annual return | Within seven months after the financial year end for most non-listed companies (ACRA) |
| Corporate income tax return | 30 November of the Year of Assessment; for YA 2026 the deadline is 30 November 2026 (IRAS) |
The audit needs to be completed in time for the audited financial statements to be presented at the AGM or sent to members, so in practice the audit timeline is driven by the six-month AGM deadline, not the annual return deadline.
Before the year end: plan the audit
- Agree the scope and timetable early. Confirm the engagement, the financial reporting framework, the reporting deadline to head office if there is one, and who in your team is the main contact.
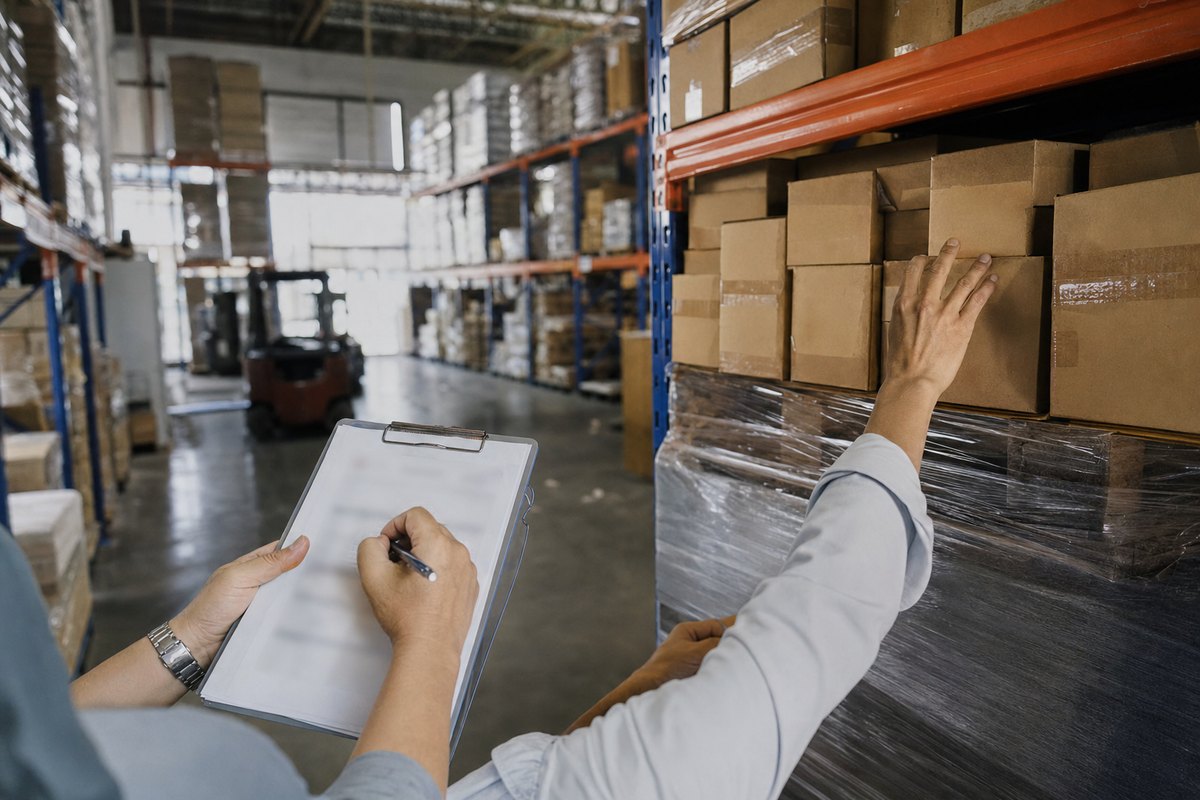
- Plan the stock count. If inventory is material, the auditor will usually want to attend or observe a count at or near the year end. Agree the date, the count instructions and how cut-off will be handled before the year end, not after.
- Identify unusual transactions. Capital injections, related party loans, leases, new contracts with customers and any government grants all tend to need documents and judgement. Flag them early.
- Collect the incorporation pack. Constitution, share allotment records, register of members, directors’ resolutions and the auditor’s appointment are among the first items an auditor asks for in a first audit.
At the year end: close the books properly
- Reconcile every bank account to the bank statement at the year-end date, and list reconciling items with explanations.
- Run aged lists of receivables and payables and agree them to the general ledger.
- Record accruals for expenses incurred but not yet invoiced, and deferred income for amounts billed in advance.
- Update the fixed asset register and depreciation, and check that additions have invoices.
- Reconcile intercompany balances with head office and other group companies, in both currencies if they differ.
- Record the final stock count results and investigate significant differences.
Confirmations: start them early
External confirmations are a common source of delay. Banks, customers, suppliers, lawyers and group companies each reply at their own pace. Prepare a list of banks (including dormant accounts and fixed deposits), major customers and suppliers, and any lawyers who acted for the company, with correct contact details. Where head office is overseas, let the group finance team know that a confirmation request will arrive and who should sign it.
The audit fieldwork: what usually gets requested
- Trial balance and general ledger in a spreadsheet-friendly format
- Bank statements and reconciliations for all accounts
- Sales invoices, contracts and delivery records for a sample of transactions
- Purchase invoices and payment approvals for a sample of expenses
- Payroll reports, employment contracts for key staff and CPF records
- Tenancy agreements, loan agreements and any significant contracts
- GST returns if the company is GST-registered
- Board minutes and written resolutions for the year and up to the audit date
Opening balances deserve special attention in a first audit. If the company has traded for some years without an audit, the auditor will need evidence that the opening position is free of material misstatement, which may involve looking back at prior-year records.
After the audit: AGM and annual return
Once the financial statements are finalised and signed, the company holds its AGM within six months after the financial year end. A private company does not need to hold an AGM if it sends its financial statements to all members within five months after the year end, or if all members have passed a resolution to dispense with AGMs; members can still require a meeting within the prescribed period (ACRA, AGM requirements).
The annual return is then filed with ACRA. For most non-listed companies the deadline is seven months after the financial year end; ACRA lists a longer period for non-listed companies with a share capital that keep an overseas branch register (ACRA, annual return deadlines). Late filing attracts a penalty of $300 if filed up to three months after the deadline and $600 after that, and ACRA can take further enforcement action (ACRA, penalties).
From 20 October 2026, filers also need to confirm that the details ACRA holds for directors, the CEO, the company secretary, auditors and relevant members are up to date when filing the annual return, and the eform includes an additional question on the CEO role (ACRA announcement). It is worth checking these details in Bizfile before the filing date.
A realistic timeline for a 31 December year end
| When | What to do |
|---|---|
| October to November | Agree audit plan, stock count date and confirmation list |
| 31 December | Year end, stock count, cut-off |
| January to February | Close the books, send confirmations, prepare schedules |
| By 31 March | File ECI if required |
| March to May | Audit fieldwork, adjustments, draft financial statements |
| By 30 June | AGM, or the private company alternatives |
| By 31 July | Annual return with ACRA |
| By 30 November | Corporate income tax return |
This is a planning illustration only. Your own dates depend on your financial year end, the size of the company and any reporting deadlines set by head office.
Talk to us
If you would like a second view on planning your first audit, the Lee Kim Audit team can walk through your situation with you. Email Help@LeeKimAudit.com or call +65-6633-5051. Korean-language support is available.
Important: This article is general information only and is not professional, legal or tax advice. Rules, thresholds and deadlines change, and how they apply depends on your company’s facts. Please check the official ACRA or IRAS source referred to above, or speak with the audit team, before acting on anything here. Information was checked against official sources on 16 November 2026.


